
What if the largest cost of placing your Massachusetts home in an irrevocable trust isn’t the deed fee, but the control you give up? If you’re asking how much does an irrevocable trust cost for a house, it’s understandable to want a clear figure before making a major decision. The total depends on more than drafting. Legal planning, deed preparation and recording, and ongoing responsibilities may all affect the overall cost.
Before transferring a home, understand what the trust may let you change later and what it may not. An irrevocable trust may support goals such as asset protection, tax planning, or long-term-care planning, but transferring ownership can affect who makes future decisions about the property. The right approach depends on your circumstances and priorities.
This guide explains the main cost categories involved in placing a home in a Massachusetts irrevocable trust, why local property-transfer steps matter, and what to consider about control and future plans. You’ll also find practical information to gather before an estate-planning discussion, so you can evaluate the tradeoffs with greater confidence.
Key Takeaways
- There’s no single answer to how much does an irrevocable trust cost for a house. The overall budget may include legal planning, deed work, recording, and administration.
- Understand how the roles of grantor, trustee, and beneficiaries determine who may make decisions about a home held in trust.
- Separate one-time setup tasks from possible ongoing responsibilities to build a clearer cost picture.
- Before deciding, identify your planning goal, review how the home is owned, and consider how much control you need to retain.
- A personalized estate-planning discussion can clarify the proposed scope, fees, and tradeoffs, including how legal work differs from third-party charges.
How Much Does an Irrevocable Trust Cost for a House in Massachusetts?
There’s no single reliable fee for every irrevocable trust holding a house. The cost depends on the legal work and the steps needed to transfer and manage that specific property. A plan for a home owned by one person with straightforward title may require different work from a plan involving co-owners, a mortgage, older deed records, or several beneficiaries.
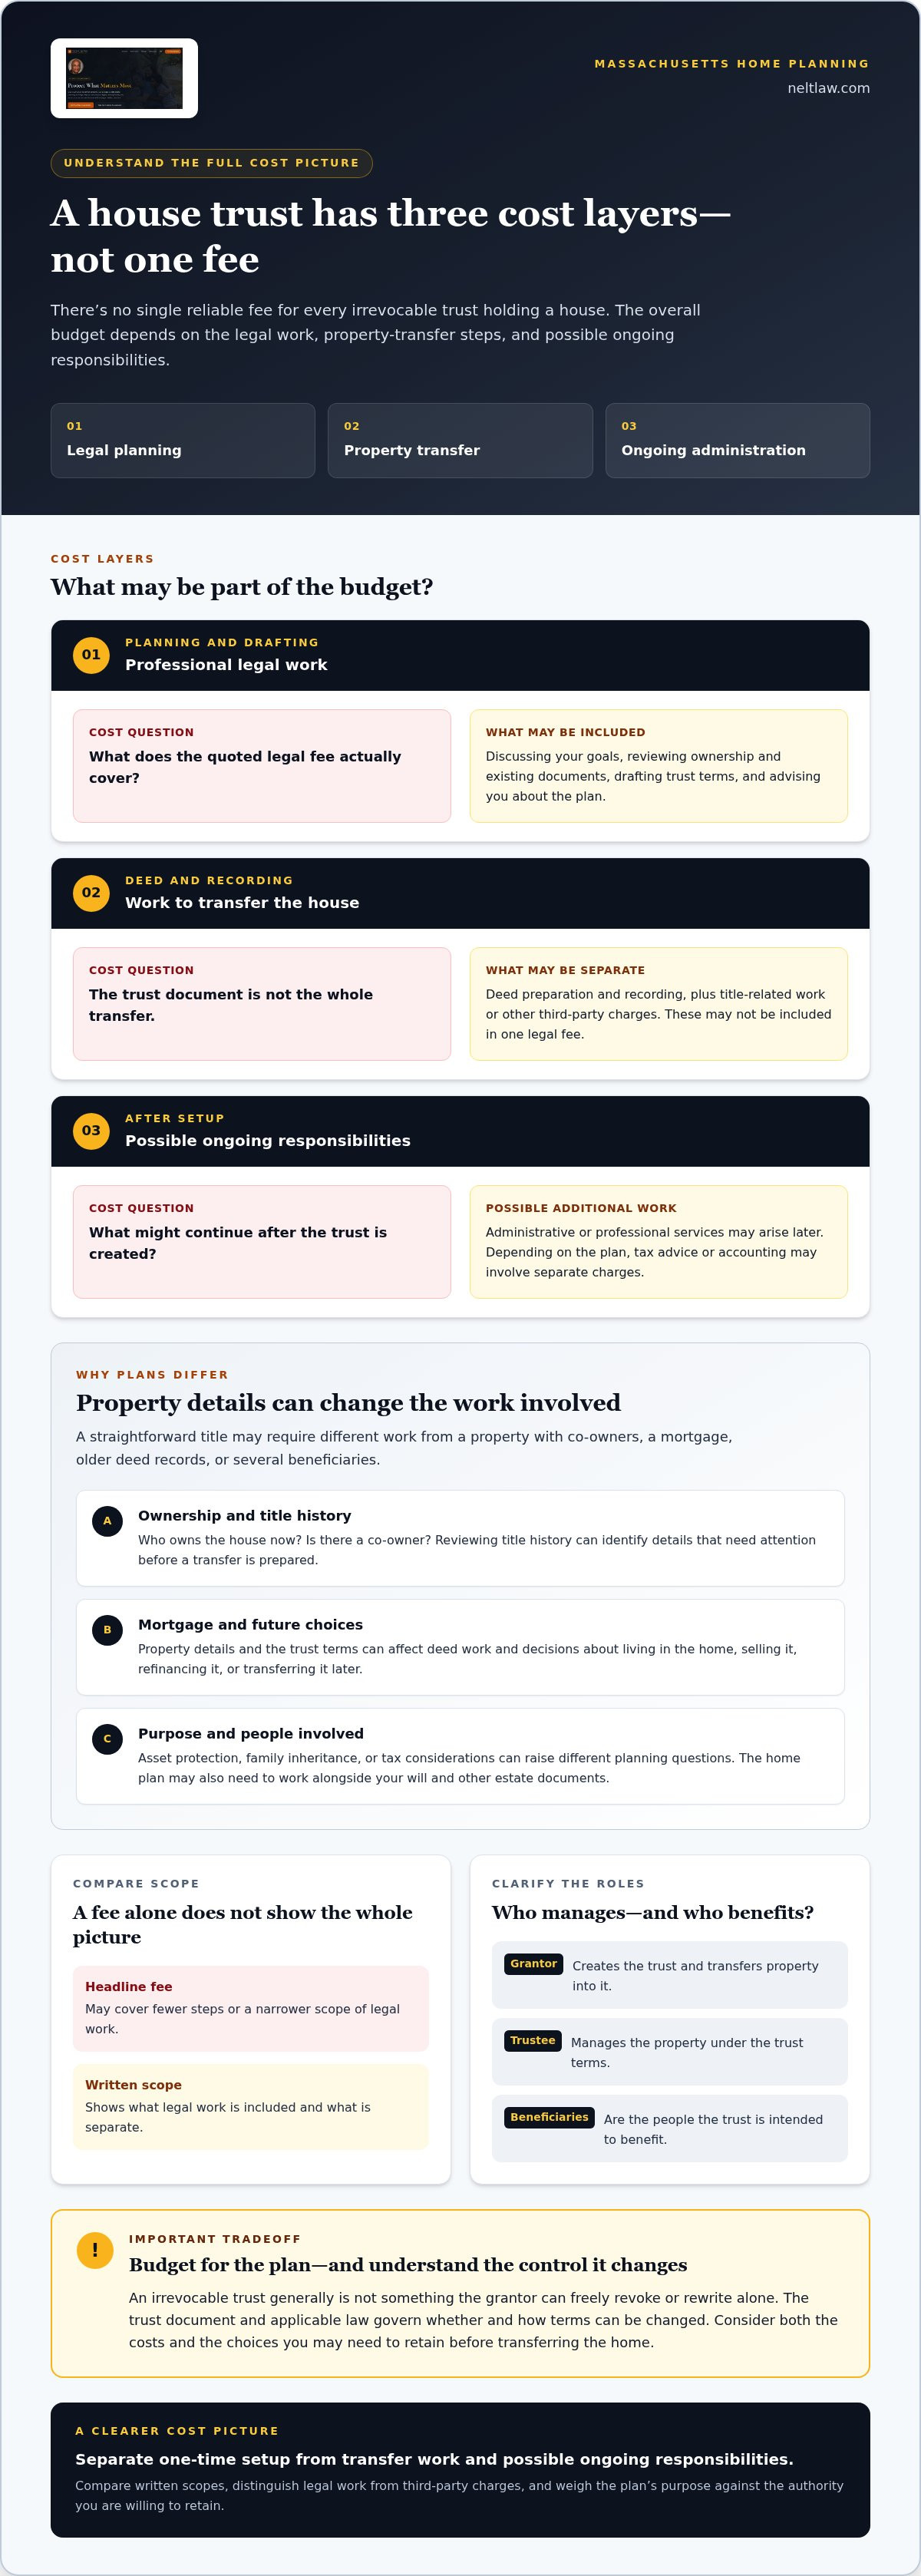
Total trust cost includes setup, property transfer, and ongoing administration. The budget may include legal planning and drafting, deed preparation, recording, and later administrative or professional services. These categories are related, but they aren’t necessarily included in one legal fee.
The trust’s purpose also affects the work involved. Planning for asset protection may raise different questions from planning focused on family inheritance or tax considerations. The home’s ownership history and property details matter because the trust must fit the real estate and the owner’s broader plan, not just a generic document template.
What does the quoted legal fee usually describe?
An attorney’s fee generally covers professional work such as discussing your goals, reviewing ownership and existing documents, drafting trust terms, and advising you about the plan. The precise scope can vary. Ask for a written engagement description that states what legal work is included and what is separate.
Recording, title-related work, tax advice, or accounting may involve separate third-party charges. Compare written scopes, not headline fees alone. A lower quote may cover fewer steps, while a broader scope may address more of the planning your circumstances require.
Why can a house trust cost more than a basic document?
A home transfer calls for property-specific review. Who owns the house now? Is there a co-owner or mortgage? How should the trust account for the people who may benefit from the property? These details can affect both the deed work and the trust provisions. Reviewing the title history can also identify details that need attention before a transfer is prepared.
The plan may need to work alongside your will, other estate documents, and asset-protection goals. Trusts involve distinct roles: the person creating and transferring property is often called the grantor, the trustee manages it under the trust terms, and beneficiaries may receive its benefits. The overview of Trust (law) explains these roles and the basic structure.
The transfer itself also takes work. Preparing and recording a deed goes beyond drafting trust terms, and the steps depend on the property and its ownership. A Massachusetts planning discussion should distinguish legal work from recording or other third-party charges, then explain what ongoing administration may involve. That gives you a fuller budget to weigh against the trust’s purpose.
What Does an Irrevocable Trust Mean for Your House and Your Control?
Putting a house into an irrevocable trust changes more than the name on a deed. The grantor creates the trust and transfers property into it. The trustee manages that property under the trust’s terms, while the beneficiaries are the people the trust is intended to benefit. These roles may belong to different people, so clarify who will make decisions and who may benefit.
An irrevocable trust generally isn’t something the grantor can freely revoke or rewrite alone. The trust document and applicable law govern whether and how its terms can be changed. Cornell Law School’s Irrevocable Trust Definition offers a concise explanation of this central feature. Understand the restrictions before transferring your home, rather than waiting until a future decision becomes urgent.
Trust suitability depends on both the protection you intend and the authority you’re willing to retain. A lower drafting fee can’t make up for terms that leave you without flexibility you need. So, consider the question of how much does an irrevocable trust cost for a house alongside another question: what choices about the home will I still be able to make?
What control may change after transferring a home?
Once the house is held in trust, the trustee’s authority comes from the trust terms rather than from the grantor’s personal ownership of the property. Those terms affect who can make decisions about living in the home, selling it, refinancing it, or transferring it later. For example, a homeowner who expects to sell or borrow against the house should consider how the trust handles those choices. Don’t assume you can act as before.
Potential effects on creditors, taxes, or long-term-care planning also depend on the specific plan and individual circumstances. A trust shouldn’t be treated as a guaranteed result. Review how the arrangement fits your needs before relying on it for a particular purpose.
When might an irrevocable trust deserve consideration?
Some homeowners explore irrevocable trusts as part of planning for asset protection, family continuity, or future long-term care. Whether a trust fits depends on the goal, timing, eligibility rules, ownership, and personal circumstances. If Medicaid planning is part of your concern, this Massachusetts asset-protection strategies guide provides related context.
Before deciding, write down what you want the home plan to accomplish and which decisions you may need to make in the future. A conversation with Northeast Legal Team’s estate-planning attorneys can help you consider those goals alongside the trust terms and broader estate plan.
Which House-Related Expenses Can Add to Irrevocable Trust Costs?
A home trust budget can include more than preparing the trust document. To see what may apply, separate the work into three categories: legal planning, transferring the property, and administering the trust over time. Some tasks are one-time steps; others may arise later, depending on the trust terms and the home’s circumstances.
| Expense category | What it may involve | Why it varies |
|---|---|---|
| Legal drafting and review | Discussing your goals, reviewing ownership and existing estate documents, preparing trust terms, and advising on the plan. | The trust’s purpose, your circumstances, and the documents requiring coordination shape the scope. |
| Deed and recording work | Reviewing title information, preparing a deed, completing execution steps, and recording the transfer. | Ownership history, co-owners, mortgage details, and property-specific questions can affect the work. |
| Ongoing administration | Trustee recordkeeping, possible tax-return preparation, and professional advice as questions arise. | Responsibilities depend on the trust terms, assets held, and circumstances over time. |
What may be involved in transferring a Massachusetts home?
Transferring a house is a sequence, not just a document signing. First, title information is reviewed to understand who owns the property and whether the records raise questions. A deed is then prepared and executed as appropriate, followed by recording with the Registry of Deeds responsible for the property’s location. Middlesex and Worcester County each have Registry of Deeds offices. The correct office and current recording procedures depend on the specific property.
Before any transfer, have an attorney review how the deed may interact with a mortgage, homestead protections, taxes, and existing ownership arrangements. A title review may reveal co-owners, prior transfers, or other record details that need attention. These checks help avoid treating a home transfer as a routine formality when its history or ownership calls for a tailored approach.
What ongoing responsibilities can create future expenses?
After the deed and trust documents are prepared, the trustee may need to keep records of trust activity and seek accounting, tax-return preparation, or legal advice when questions arise. These are potential administrative needs, not automatic expenses in every plan. Their nature and frequency depend on the trust terms, the assets it holds, and what happens over time.
Keep recurring administration separate from one-time document preparation and deed recording when building a budget. Ask for a written scope that distinguishes legal planning from recording or other third-party charges. For a useful discussion, gather the current deed, mortgage information, ownership details, and relevant estate documents. Then you can consider how much does an irrevocable trust cost for a house in light of the actual transfer steps and responsibilities, rather than relying on a general estimate that may not fit your property.
How Can You Assess Whether the Cost and Tradeoffs Fit Your Situation?
A trust decision is easier to evaluate when you separate what you want to accomplish from the document itself. The least expensive document may not address questions about the home’s title, family arrangements, taxes, or future care. Instead of choosing based on price alone, work through the purpose, ownership, control, and scope in that order. This helps you assess whether the proposed plan fits your life as well as your budget.
- Identify the goal. Name the concern you want to address, such as protecting family continuity or planning for possible future care.
- Review ownership. Gather the deed and clarify who owns the home, along with any mortgage or shared-ownership details.
- Assess control needs. Consider whether you may need flexibility to occupy, sell, refinance, or otherwise make decisions about the property.
- Discuss the scope. Review the legal planning and property-transfer work involved, what may be charged separately, and what responsibilities could continue.
What should you compare before committing to a trust?
Compare the intended protection with the authority you’ll retain, your family’s needs, and the work of administering the arrangement. A house-focused irrevocable trust may involve a different control tradeoff from a revocable trust or other estate-planning tools. Neither approach is automatically right. Consider how each option fits your goals and the choices you may want to make later.
Also review how the plan fits with your will, power of attorney, and beneficiary arrangements. If Medicaid planning is a key concern, the Massachusetts asset-protection trust cost guide offers related context. Eligibility and outcomes depend on individual circumstances, so use the discussion to identify questions for personalized legal review.
How can you prepare a useful cost discussion?
Bring the current deed, mortgage information, ownership details, and existing estate-planning documents. Write down who you hope to benefit, whether you expect to keep living in the home, and any concerns about future care. These details make the conversation specific to your household rather than a comparison of generic document prices.
Ask for a clear explanation of the legal scope, property-transfer work, possible third-party charges, and future administrative responsibilities. A written outline makes it easier to see what is included and where separate work may arise. You can also discuss alternatives and tradeoffs before deciding, rather than treating the proposed trust as the only path.
If you’re weighing a house transfer, schedule an estate-planning discussion with Northeast Legal Team to review your goals, ownership details, and the scope of a plan. A thoughtful conversation can help you understand what you’d be paying for and what authority you may be giving up.
How Northeast Legal Team Can Help Plan an Irrevocable Trust for a House
Planning starts with your reasons for considering a trust, not with a standard document. Northeast Legal Team helps individuals and families consider trusts within a broader estate plan, taking account of family goals, home ownership, and existing plans. A homeowner hoping to keep living in the house may have different questions from someone focused on how the property will pass to loved ones.
A free, no-obligation consultation or assessment gives you a place to discuss whether this kind of planning may fit. Explain what you hope to accomplish, raise concerns about control, and discuss what information may help clarify next steps. If you’re asking how much does an irrevocable trust cost for a house, a useful first conversation explores the work involved in your circumstances rather than assuming every home or trust has the same scope.
What happens during an initial planning conversation?
Bring the property details you have, including the current deed, any mortgage information, and who owns the home. It also helps to share family priorities, intended beneficiaries, occupancy plans, concerns about future care, and relevant estate documents. Counsel can use these facts to discuss possible planning approaches, tradeoffs, and next steps. You can also clarify which legal work may be involved and which property-related or third-party expenses may be separate.
What should a written estate-planning scope make clear?
Before work begins, understand which services the engagement covers. Depending on the agreed scope, questions to resolve may include trust drafting, review of existing documents, signing or execution guidance, and deed or property-transfer work. A written description can distinguish the attorney’s professional services from recording or other third-party charges, as well as future trust administration.
Northeast Legal Team offers fixed-fee legal services for estate-planning documents, but a fixed fee doesn’t mean every trust plan has the same scope or price. The work is shaped by the homeowner’s goals, property details, and broader plan. Clarify what the quoted legal work includes, what falls outside it, and how questions or additional work would be handled. This makes it easier to understand the full commitment instead of comparing headline fees alone.
It can also help to discuss how the deed transfer will be addressed, whether existing estate documents need review, and what responsibilities may continue after setup. These questions make the discussion practical and help surface gaps before you commit. For a broader explanation of how flat-fee arrangements can be structured, see this estate-planning flat-fee guide.
Once you’ve gathered your documents and questions, schedule a free, no-obligation consultation or assessment with Northeast Legal Team. The conversation can help you understand the proposed scope and tradeoffs, then decide on a next step at your own pace.
Take the Next Step With a Clear Plan
Your next step doesn’t have to be a commitment to transfer your home. Start by deciding what you need to understand before making that choice: how the plan would fit your family, what decisions you’d want to retain, and what work the proposed scope covers. Bringing those questions to a legal-planning conversation can help turn uncertainty into a decision you can make with care.
If you’re still asking how much does an irrevocable trust cost for a house, focus on getting a clear explanation of the work and tradeoffs involved in your circumstances. Northeast Legal Team offers flat-fee estate-planning services and works with Massachusetts families in Middlesex and Worcester Counties. A fee structure can clarify legal scope, while property-related and other third-party expenses may need to be considered separately.
Take time to understand your options before deciding what feels right. Schedule a free, no-obligation estate-planning consultation with Northeast Legal Team to discuss your goals and possible next steps.
Frequently Asked Questions
How much does it cost to put a house in an irrevocable trust in Massachusetts?
There’s no dependable amount that applies to every homeowner. If you’re asking how much does an irrevocable trust cost for a house, the answer depends on the plan and property-specific work, including trust design, title history, deed preparation, recording, and possible administration. A home with co-owners or a mortgage may call for additional review. Request a written scope that distinguishes legal work from transfer-related and future expenses.
Can I put a mortgaged house into an irrevocable trust?
Possibly, but a mortgage alone doesn’t determine whether the transfer is suitable. Before changing title, review the loan documents, ownership structure, proposed trust terms, and potential lender or tax consequences. Understand how the planned transfer relates to the existing loan before signing a deed. A Massachusetts estate-planning attorney can review the documents and explain issues specific to the property and plan.
Does transferring my house to an irrevocable trust mean I lose control?
It can change who holds title and who has authority to make decisions, but the effect depends on the trust terms and applicable law. For instance, the trustee may need to participate in a decision about selling or refinancing if the document gives the trustee authority over that action. Before transferring the home, clarify which decisions you can make yourself and what approval the trust may require.
What happens to my house after I transfer it to an irrevocable trust?
The deed and trust document establish how the house is held and managed. The trustee must follow the trust’s instructions and applicable duties, while the document helps determine how occupancy, expenses, a sale, or a later transfer will be handled. Keep copies of the signed trust and recorded deed with your estate-planning records, and make sure the people who may need to administer your plan can locate them.
Are there ongoing costs after setting up an irrevocable trust for a house?
There may be future administration work, depending on the trust’s activity and terms. For example, the trustee may need to maintain records or coordinate tax preparation and professional advice. Before signing, clarify who is expected to handle those tasks and how the plan addresses expenses connected to the house. Ask which services are part of the initial legal engagement and which may arise separately later.
Is an irrevocable trust better than a revocable trust for a house?
Neither option is automatically better. Each fits different priorities and brings different tradeoffs. A homeowner who values flexibility to change the plan may weigh a revocable trust differently from someone considering an irrevocable structure for a specific planning goal. Compare the effect on control, family arrangements, administration, and the intended outcome. Massachusetts counsel can help assess the options alongside your full estate plan.
Do I need to record a new deed when placing a Massachusetts house in trust?
A change in ownership generally needs to be documented through a deed, and the correct preparation and recording steps depend on the property and circumstances. The Registry of Deeds for the property’s location matters: a home in Middlesex County and one in Worcester County may involve different local recording offices. Review the current procedures for the relevant Registry and consider title implications before completing the transfer.


