
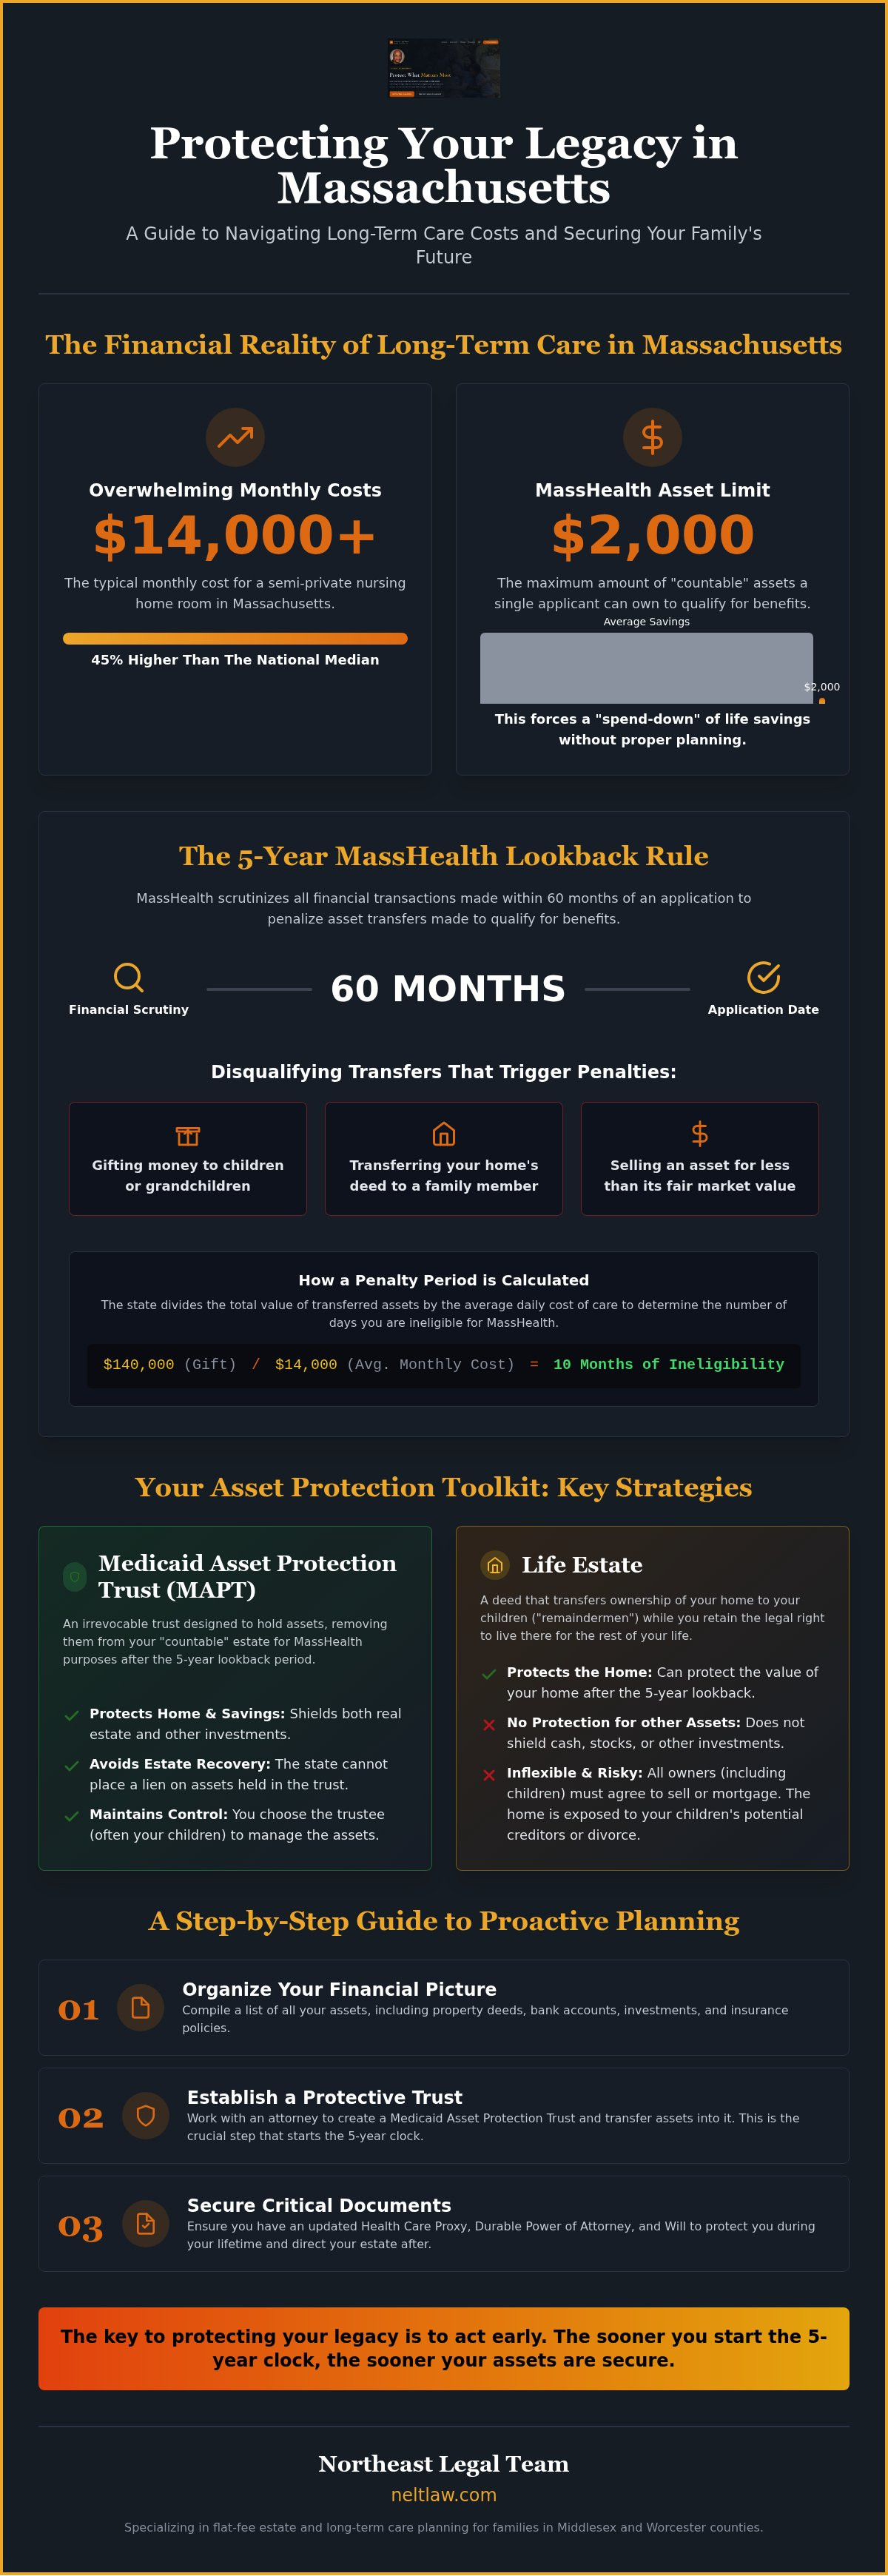
Did you know that nursing home costs in Massachusetts are now 45% higher than the national median, often exceeding $14,000 per month? For many families in Middlesex and Worcester counties, this reality creates a deep fear that a lifetime of savings will disappear in a matter of months. If you're wondering how to protect assets from nursing homes in MA, you aren't alone in your anxiety. It's common to feel overwhelmed by the state's strict $2,000 asset limit and the complex five-year lookback rule that seems to penalize even the simplest gifts to grandchildren.
We believe that planning for the future should bring a sense of relief, not more stress. You've worked hard to build a legacy, and you deserve to see it pass to the next generation rather than being consumed by long-term care bills. This 2026 guide provides a clear path to qualifying for MassHealth while keeping your home and savings safe. We will walk through the specific legal tools that shield your equity and explain how a flat-fee plan can replace your worry with a certain, secure future for your family.
Key Takeaways
- Understand why Massachusetts long-term care costs are unique and how to distinguish between private pay options and MassHealth eligibility.
- Discover how to protect assets from nursing homes in MA by navigating the 5-year lookback rule with clarity and confidence.
- Compare the Medicaid Asset Protection Trust against Life Estates to find the right shield for your family home and life savings.
- Follow a simple, step-by-step process to organize your estate and establish the critical legal documents needed for long-term security.
- Learn how a flat-fee planning model eliminates the stress of the billable hour while ensuring you have a dedicated advocate by your side.
The Reality of Nursing Home Costs in Massachusetts
Massachusetts consistently ranks as one of the most expensive states for long-term care. It's not just your imagination; the data confirms that a semi-private room here often costs over $14,000 every month. For families in Middlesex and Worcester, these figures can feel like a ticking clock against your family's inheritance. Most people realize too late that their private health insurance or Medicare won't cover these bills. This leaves families with three difficult choices: paying out of pocket until they're broke, relying on a long-term care insurance policy, or qualifying for MassHealth. Many families find that Understanding MassHealth, the state's version of Medicaid, is the only way to manage these overwhelming costs. Learning how to protect assets from nursing homes in MA is a necessity for anyone who wants to preserve their legacy.
The Spectrum of Care in MA
Long-term care isn't a single destination. It often begins with in-home care or assisted living before progressing to a skilled nursing facility. While Medicare covers short-term rehabilitation, it doesn't pay for the long-term custodial care most seniors eventually need. This gap leads many into the spend-down trap. This is a stressful period where you're told you must spend your assets until you have only $2,000 left. It feels overwhelming because the rules are complex. However, you don't have to wait for a crisis to take action. Proactive planning allows you to set the terms of your care without losing your financial independence. When you understand how to protect assets from nursing homes in MA, you can avoid the desperation of a last-minute spend-down.
Protecting the Family Home in Middlesex and Worcester
Your home is likely your most significant investment, especially with the strong real estate values we see across Middlesex and Worcester counties. If you require long-term care, the state may look at your property as a way to pay for those services. MassHealth estate recovery is a real risk; the state can place a claim on your home after you pass away to recoup what they spent on your care. While the 2026 home equity limit is $1,097,000, this only protects the home during your lifetime. Leaving your property's fate to chance is the most expensive strategy you can have. By using proven legal tools now, you can ensure your home stays in the family for generations to come. It provides a sense of relief to know the roof over your head is secure, regardless of future health changes.
Understanding MassHealth and the 5-Year Lookback Rule
MassHealth is the Massachusetts version of the federal Medicaid program. While many people think of it as insurance for low-income individuals, it's also the primary way seniors pay for long-term care in our state. However, you can't simply give away your money today and expect the state to pick up the bill tomorrow. If you want to know how to protect assets from nursing homes in MA, you must understand the rules of the game. The state looks back at every financial transaction you've made over the last 60 months to ensure you haven't intentionally lowered your net worth just to qualify for benefits.
The Lookback Period is a window of financial scrutiny. During this time, MassHealth examiners review bank statements, property transfers, and even small gifts to family members. A disqualifying transfer occurs when you sell an asset for less than its fair market value or give it away entirely. Even well-intentioned gifts, like helping a grandchild with college tuition, can trigger a penalty if they happen within that five-year window. This is why proactive planning is so vital; the earlier you start, the easier it is to move assets outside that window of scrutiny. You can find more details on these specific regulations through the official MassHealth and the 5-Year Lookback Rule resources.
How the Penalty Period is Calculated
If the state finds a disqualifying transfer, they don't just deny you forever. Instead, they calculate a penalty period. They take the total amount you gave away and divide it by the average daily cost of nursing home care in Massachusetts. For example, if you gave away $140,000 and the state determines the monthly cost is $14,000, you would be ineligible for benefits for ten months. A common misconception is that "giving the house to the kids" is a quick fix. In reality, transferring a deed within the lookback period often creates a massive penalty that leaves the family stuck paying for care out of pocket. If you're concerned about how these rules apply to your specific accounts, our team can help you navigate the Asset Protection process with a clear, flat-fee plan.
Countable vs. Non-Countable Assets
To qualify for MassHealth, a single applicant can only have $2,000 in countable assets. It's a shockingly low number that often causes immediate panic. Countable assets include things like checking accounts, stocks, and secondary properties. However, there are non-countable assets that the state ignores during the initial application process:
- Your primary residence, as long as your equity is below $1,097,000.
- One vehicle used for transportation.
- Personal belongings and household goods.
- Certain prepaid funeral arrangements.
While these assets are "exempt" for eligibility, they aren't necessarily safe from estate recovery after you pass away. This is the hidden trap of "doing nothing." Understanding how to protect assets from nursing homes in MA means looking beyond just qualifying today; it's about securing your family's future for years to come. By identifying which assets are vulnerable now, you can take the steps necessary to shield them from future claims.
Asset Protection Tools: Trusts vs. Life Estates
Choosing the right legal tool is the most important decision you'll make when securing your family's future. While there are many ways to organize an estate, not all of them shield you from the high costs of long-term care. In fact, a standard revocable living trust, while excellent for avoiding probate, offers zero protection against MassHealth. If you want to know how to protect assets from nursing homes in MA, you must focus on irrevocable strategies that satisfy the state's strict requirements. Two primary options stand out for families in our community: the Medicaid Asset Protection Trust and the Life Estate.
The Medicaid Asset Protection Trust (MAPT)
The MAPT is widely regarded as the gold standard for asset protection in Massachusetts. By placing your home or savings into this irrevocable trust, you effectively move them out of your "countable" asset column. You can't reach into the trust to spend the principal whenever you like, but you can still receive any income the trust generates. Most importantly, you retain the right to live in your home for the rest of your life. This tool is designed to provide safety while maintaining your lifestyle. If you're considering this path, it's helpful to research the specifics of understanding Medicaid Asset Protection Trust cost in Massachusetts to see how it fits into your overall plan.
A MAPT requires a trustee, often an adult child or a trusted family friend, to manage the assets. This structure ensures that even if you require nursing home care later, the assets held within the trust remain untouched by the state once the five-year lookback period has passed. It provides a level of certainty that few other legal instruments can match. It's a way to say "this is for my children" in a way that the law respects and protects.
Life Estates and Rights of Occupancy
For some homeowners, a Life Estate offers a simpler alternative to a trust. This legal arrangement allows you to "split" the ownership of your property. You keep a life interest, which gives you the absolute right to live in and use the home until you pass away. Simultaneously, you transfer the "remainder interest" to your heirs. This is a popular method for how to protect assets from nursing homes in MA because it's straightforward and avoids the complexity of ongoing trust management. When you pass away, the home goes directly to your children without the need for probate.
However, Life Estates do come with trade-offs. Unlike a trust, a Life Estate makes your children legal co-owners immediately. If you decide to sell the house while you're still living, your children must agree to the sale, and a portion of the proceeds would technically belong to them. This can sometimes create tax complications or issues if a child faces their own financial troubles. We often help families weigh these risks against the simplicity of the deed transfer to ensure they feel confident in their choice. Whether a trust or a Life Estate is better depends entirely on your family's unique goals and the level of flexibility you need for the future.
A Step-by-Step Guide to Proactive Planning
Taking the first step toward long-term security often feels like the hardest part, but having a clear roadmap can turn that anxiety into action. If you're wondering how to protect assets from nursing homes in MA, the process is less about complex math and more about intentional organization. By breaking the journey into manageable steps, you can regain a sense of control over your family's future. This proactive approach ensures that your hard-earned savings stay where they belong: with your loved ones.
- Step 1: Inventory your assets. This is your primary "homework" before meeting with a professional. Create a comprehensive list of everything you own, including bank accounts, retirement funds, and property deeds. Knowing exactly what you have allows you to identify which assets are most vulnerable and need immediate protection.
- Step 2: Establish your Healthcare Proxy and Power of Attorney. You need to name trusted individuals to make decisions on your behalf if you cannot. Without these documents, your family might have to go through a costly and public court process to help you.
- Step 3: Consult with an elder law attorney. A specialist can help you choose the right trust structure for your specific needs. Whether it's a Medicaid Asset Protection Trust or a Life Estate, professional guidance ensures the plan meets Massachusetts' strict legal standards.
- Step 4: Fund the trust. A trust is just a stack of paper until you "fund" it. This involves physically transferring titles and accounts into the name of the trust. This step is critical for how to protect assets from nursing homes in MA because only assets correctly titled are shielded from the state.
- Step 5: Wait out the lookback period. Once the assets are transferred, the five-year clock begins. We provide professional monitoring to ensure your plan remains compliant with any changing state regulations during this window.
Foundational Documents You Need Now
While trusts protect your money, foundational documents protect your person. Consulting a living will attorney is essential for maintaining your medical autonomy. A living will or healthcare directive ensures your wishes regarding medical treatment are honored, even if you become incapacitated. Similarly, a Durable Power of Attorney gives a loved one the legal authority to manage your finances and protect your assets if a sudden illness occurs. These documents provide the peace of mind that your voice will always be heard.
Crisis Planning: Is it Ever Too Late?
Many families worry that because they didn't plan five years ago, they've lost everything. This isn't true. Even if a loved one needs a nursing home immediately, there are emergency spend-down tactics available. Strategies like the "Half-a-Loaf" method allow families to gift a portion of their assets while using the remaining funds to pay for care during the resulting penalty period. While proactive planning is always better, even a late start can save a significant portion of the family estate. If you're facing an immediate need, you can schedule your free assessment to explore your options today.
The Northeast Legal Team Flat-Fee Advantage
When you're trying to figure out how to protect assets from nursing homes in MA, the last thing you need is the added stress of an unpredictable legal bill. Many traditional law firms charge by the hour, which often makes families hesitant to pick up the phone or ask a clarifying question. We believe that this "meter is running" mentality creates a barrier to effective planning. At Northeast Legal Team, led by David E. Walker, Esq., we've replaced the billable hour with a transparent, flat-fee model. This approach allows us to focus entirely on your family's well-being rather than tracking minutes on a clock. It transforms the legal process from a cold transaction into a supportive partnership.
Our firm takes the role of a compassionate mentor for families throughout Middlesex and Worcester counties. We understand that discussing long-term care and inheritance can feel heavy and emotional. That's why we prioritize a "listen-first" attitude, ensuring we understand the human story behind your financial goals before we ever suggest a legal instrument. We're here to guide you through the complexities of MassHealth with a steady hand, providing the weight of professional wisdom without the intimidating jargon often found in the legal industry.
Predictable Costs for Peace of Mind
Transparency is at the heart of everything we do. By choosing an estate planning attorney flat fee model, you know exactly what your investment will be from the very start. There are no surprise invoices or hidden charges for emails and phone calls. This predictability allows for better family decision-making; you can include your children in the conversation without worrying about how much the meeting is costing. It creates an environment of trust where you're free to explore every option for how to protect assets from nursing homes in MA until you feel completely certain about your path forward.
Your Next Steps Toward Security
Securing your legacy shouldn't feel like a high-pressure sales pitch. We offer a free initial asset protection assessment to help you understand your current standing without any obligation. During this conversation, we'll review your asset inventory and discuss your specific concerns about the five-year lookback rule or the family home. To prepare for this first step, simply gather a general list of your accounts and property values. We'll handle the complex legal strategy while you focus on what matters most: your family's peace of mind.
You've spent a lifetime building your savings and creating a home filled with memories. Protecting that legacy is a vital act of stewardship, and you don't have to do it alone. By taking action today, you're replacing uncertainty with a clear, manageable plan. We're ready to stand by your side as a protective advocate, ensuring that your life's work is preserved for the people you love most. Your journey toward a secure future starts with a single, reassuring conversation.
Securing Your Family Legacy for the Years Ahead
Planning for the future is one of the kindest things you can do for your children and grandchildren. We've explored how a Medicaid Asset Protection Trust can shield your home and how foundational documents like a Power of Attorney ensure your wishes are always respected. Learning how to protect assets from nursing homes in MA doesn't have to be a source of constant worry when you have a clear, methodical roadmap to follow. Whether you're starting years in advance or facing an immediate need, there are always steps you can take to preserve what you've built.
At Northeast Legal Team, we've spent over 14 years helping families in Middlesex and Worcester counties find peace of mind. David E. Walker, Esq. provides the compassionate, mentor-like guidance you deserve, while our flat-fee pricing ensures you never have to fear the billable hour. You can take the first step toward certainty today without any pressure or obligation. We invite you to Schedule Your Free Asset Protection Assessment with Northeast Legal Team to discuss your unique story. You've worked hard for your legacy; let's work together to make sure it stays exactly where it belongs.
Frequently Asked Questions
Can MassHealth take my house if I go into a nursing home in MA?
MassHealth generally doesn't take your home while you or certain family members are still living there. However, they may place a lien on the property to secure reimbursement for the cost of your care. After you pass away, the state can seek estate recovery to collect those funds from the value of the home. This is why learning how to protect assets from nursing homes in MA is so critical for homeowners.
How far back does the Massachusetts Medicaid lookback period go?
The lookback period in Massachusetts spans exactly 60 months, or five years, from the date you apply for benefits. During this time, MassHealth reviews every financial transaction to ensure you haven't given away assets for less than their fair market value. If they find disqualifying transfers, they'll impose a penalty period where you must pay for your own care. Proactive planning helps you move assets safely before this five-year window begins.
What is a Medicaid Asset Protection Trust and how does it work?
A Medicaid Asset Protection Trust is an irrevocable legal structure designed to hold your assets so they aren't counted toward the $2,000 MassHealth limit. You transfer ownership of your home or savings into the trust, and a trustee manages them. Once the five-year lookback period passes, these assets are shielded from nursing home costs. You can still live in your home and receive income from the trust while protecting your family's inheritance.
Is it too late to protect my assets if my spouse is already in a nursing home?
It's rarely too late to take action, even if a spouse is already receiving care. This is known as crisis planning. Massachusetts law allows for specific strategies, such as the Half-a-Loaf method or converting countable assets into an immediate annuity for the healthy spouse. While proactive planning is easier, an experienced attorney can still help you save a significant portion of your estate during an immediate medical crisis or sudden nursing home admission.
Can I give $15,000 a year to my children without affecting MassHealth eligibility?
No, this is a common misunderstanding that can lead to significant penalties. While the IRS allows you to give a certain amount annually without filing a gift tax return, MassHealth has a different standard. Any gift made within the five-year lookback period, regardless of the amount, can trigger a penalty. If you're researching how to protect assets from nursing homes in MA, it's vital to distinguish between federal tax laws and state Medicaid eligibility requirements.
What assets are exempt from nursing home costs in Massachusetts?
Certain assets are considered non-countable for eligibility. These include your primary home if your equity is below $1,097,000, one vehicle used for transportation, and your personal belongings. You're also allowed to keep up to $2,000 in cash or bank accounts. While these items are exempt during the application process, they may still be subject to estate recovery later unless you've implemented specific legal protections through a trust or life estate deed.
Does a revocable living trust protect assets from a nursing home?
A revocable living trust does not protect your assets from nursing home costs. Because you maintain total control and can take the money back at any time, MassHealth considers these assets fully available to pay for your care. These trusts are excellent for avoiding probate, but they provide no shield against the spend-down process. To protect your savings, you typically need an irrevocable trust structure that meets specific Medicaid compliance standards and survives the lookback period.
How much does it cost to set up an asset protection trust in MA?
The cost of setting up an asset protection trust depends on the complexity of your estate and the specific goals of your family. At Northeast Legal Team, we believe in complete transparency, which is why we offer flat-fee pricing for our estate planning services. This model eliminates the anxiety of hourly billing and allows you to focus on the long-term security of your legacy. We provide clear, predictable pricing during your initial assessment.


