
What if the estate plan you spent weeks perfecting is actually just a stack of expensive paper that won't keep your family out of probate court? It's a common worry for many families who believe that signing the documents is the final step. However, a trust is like an empty vault; it only protects what you place inside. Learning how to fund a living trust in Massachusetts is the vital bridge between a legal document and a secure legacy. If your assets remain in your individual name, they are still subject to the public and costly probate process you worked so hard to avoid.
We understand that the thought of dealing with the Registry of Deeds or bank paperwork can feel overwhelming. You've worked hard to build your life; you don't want to leave a mess for your heirs to clean up. This guide provides a clear roadmap for transferring your assets. We'll show you how to handle the heavy lifting of asset transfers, from your primary residence to your investment accounts. By following these steps, you'll ensure your $2 million state tax exemption is utilized and your family's future is safe. It's time to move from uncertainty to the peace of mind that comes with a fully protected estate.
Key Takeaways
- Understand that a living trust only protects your assets once they are formally retitled from your individual name into the name of the trust.
- Discover the essential steps for how to fund a living trust in Massachusetts, including how to request the correct change-of-ownership forms from your bank.
- Learn how to navigate the local Registry of Deeds to transfer your real estate using a Quitclaim Deed, ensuring your home avoids the probate process.
- Identify the most common funding mistakes, such as failing to include newly purchased assets or relying solely on a notarized signature.
- Recognize how a clear roadmap and professional support can transform a complex legal task into a manageable plan for your family’s security.
Trust Funding: Why It's Critical in Massachusetts
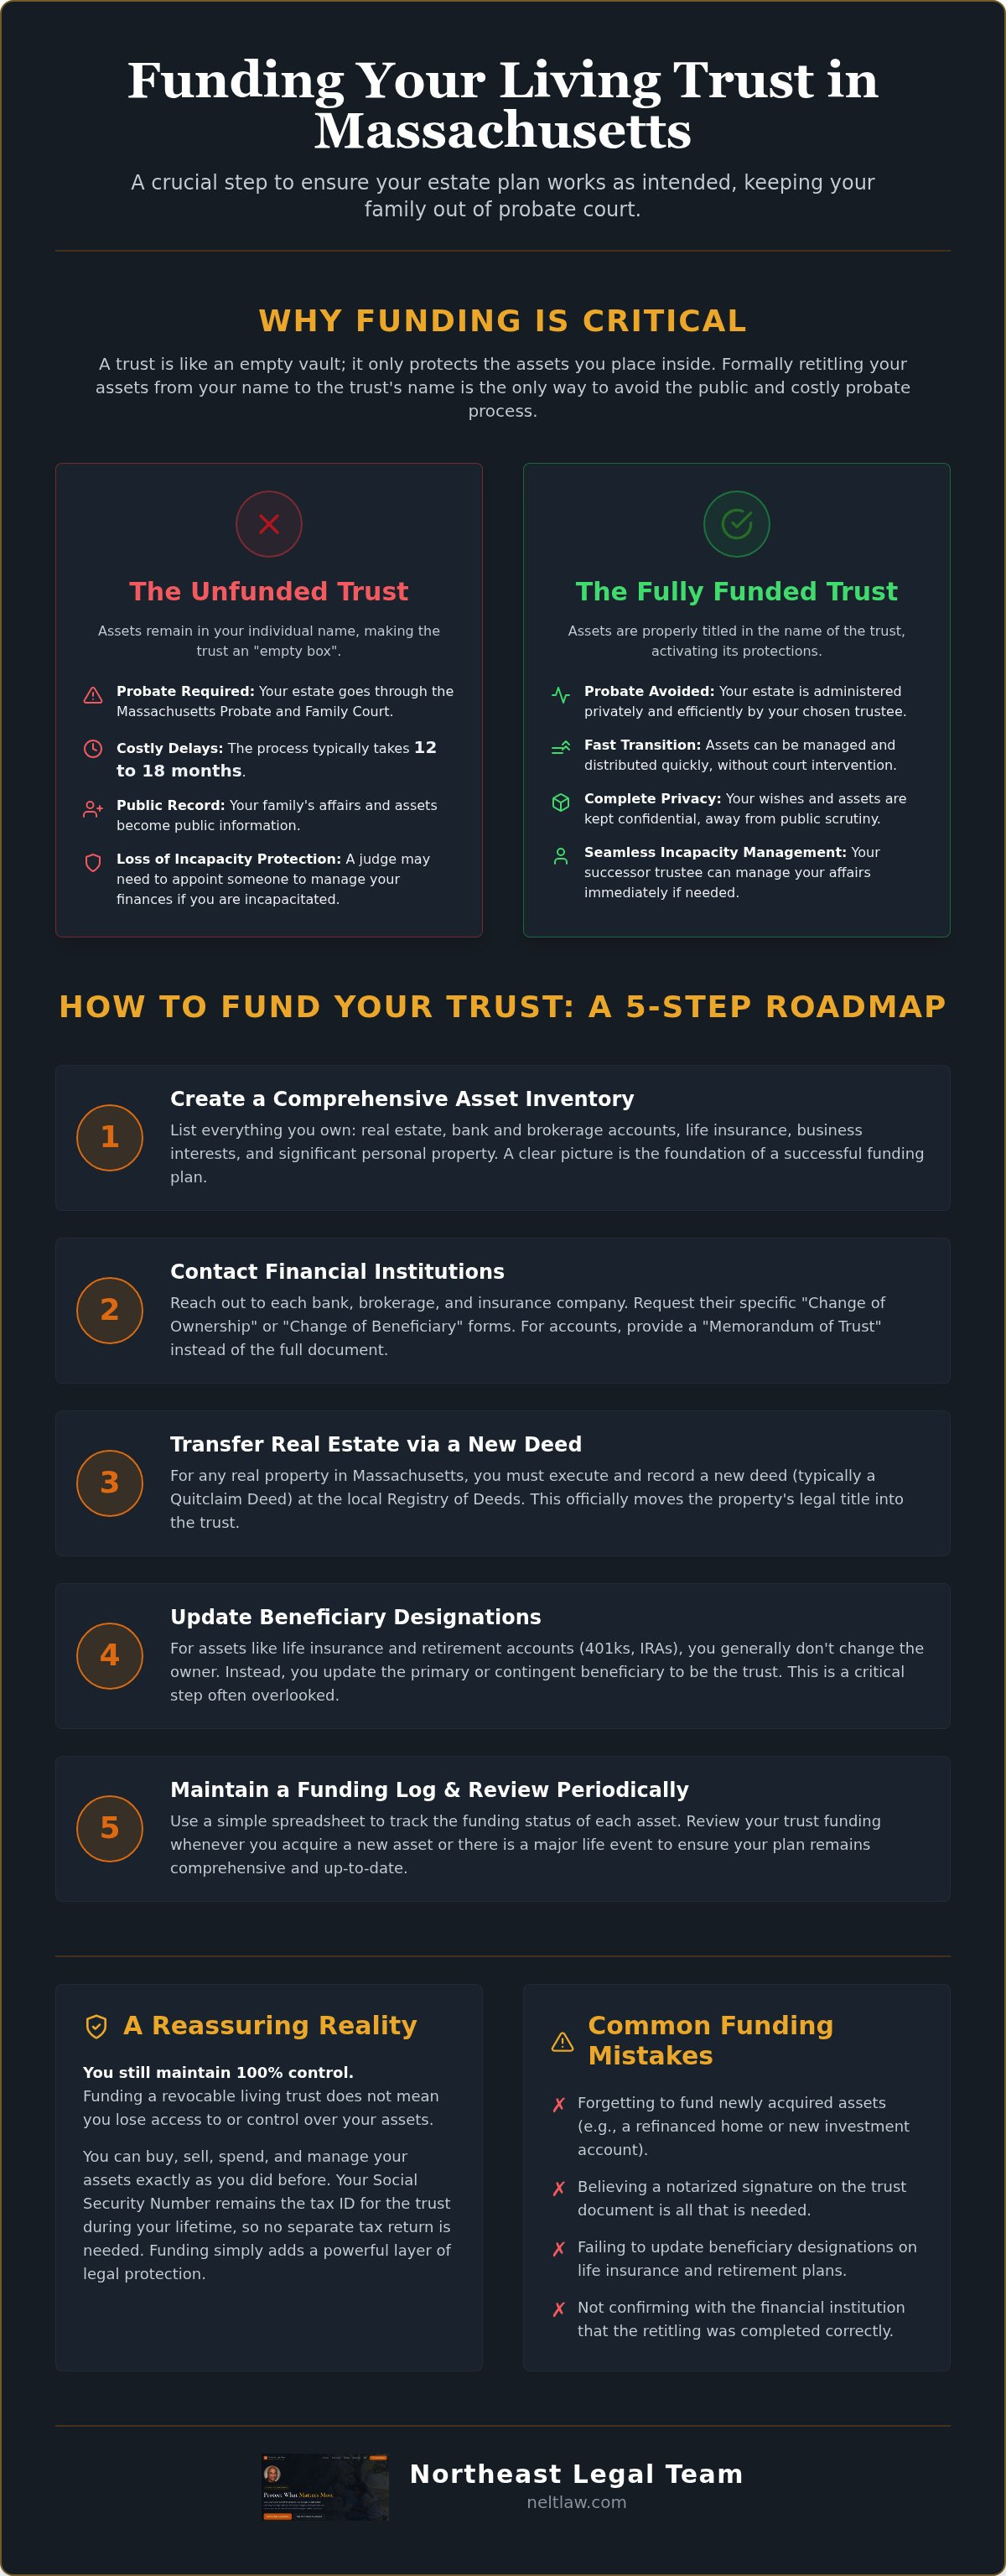
Funding isn't just a legal suggestion; it's the engine that makes your estate plan move. Many people spend hours researching What is a Living Trust and signing documents, only to stop before the finish line. Funding is the formal process of retitling your assets, like your home or bank accounts, from your individual name into the name of your trust. If you don't take this step, your trust remains an empty, ornate box. It looks beautiful on your shelf, but it holds nothing inside to protect your family when they need it most.
Understanding how to fund a living trust in Massachusetts is what truly keeps your private matters out of the public eye. Proper funding ensures your hand-picked successor trustee can step in and manage your affairs immediately if you ever become incapacitated. Without this transfer, your loved ones might have to petition a judge just to pay your utility bills or manage your investments. This simple administrative shift transforms your documents into a functional safety net.
The Cost of an Empty Trust: Avoiding Massachusetts Probate
When assets are left outside of a trust, they fall under the jurisdiction of the Massachusetts Uniform Probate Code (MUPC). This means your family must head to the Massachusetts Probate and Family Court. If you haven't mastered how to fund a living trust in Massachusetts, your family may face these hurdles in counties like Middlesex or Worcester, where the probate process often drags on for 12 to 18 months. This delay isn't just a financial drain; it's a heavy emotional burden. Grieving family members shouldn't have to navigate complex court filings and public hearings while they are trying to heal. A funded trust bypasses this entire system, allowing for a quiet, private, and much faster transition.
The Reassuring Reality: You Still Maintain Full Control
A common fear is that moving assets into a trust means losing access to them. This couldn't be further from the truth. With a revocable living trust, you remain the captain of your ship. You can buy, sell, or spend your assets exactly as you do today. Your Social Security number stays the primary tax identifier, so you don't even need to file a separate tax return for the trust during your lifetime.
Funding your trust doesn't change how you live your life; it simply changes the legal protection surrounding it.
Step-by-Step: How to Transfer Assets into Your MA Living Trust
Moving your life's work into a trust can feel like a mountain of paperwork, but it's really just a series of small, manageable tasks. The first step is to create a complete inventory of everything you own. This list should include your home, bank accounts, investment portfolios, and even digital assets. Once you have a clear picture of your estate, you'll need to contact each financial institution to request their specific "Change of Ownership" or "Letter of Instruction" forms. Every bank has its own internal process, so reaching out directly ensures you have the right documents from the start.
Mastering how to fund a living trust in Massachusetts also requires a dedicated "Funding Log." This is a simple spreadsheet or notebook where you track which assets have been moved, which forms were sent, and which items are still pending. Without this log, it's easy to lose track of a single account, which could leave your family facing the very probate process you're trying to avoid. For your real estate, you'll need to execute and record a new deed at the Massachusetts Registry of Deeds. This step is what officially moves your home's "legal title" from your individual name to the trust.
Retitling Bank and Brokerage Accounts
When you approach your bank, you don't need to hand over your entire 50-page trust document. Instead, you can provide a "Memorandum of Trust," which is a condensed version that proves the trust exists and identifies who has the authority to manage it. You'll need to decide between making the trust the direct owner of the account or using a "Transfer on Death" (TOD) designation. Direct ownership is typically the safer bet for checking and savings accounts because it allows your successor trustee to step in immediately if you're ever unable to manage things yourself. If you need a hand organizing these documents, our team can help you ensure your plan is functional and complete.
Updating Life Insurance and Retirement Accounts
Retirement accounts like 401ks or IRAs require a careful touch because of potential tax consequences. You generally won't retitle the actual owner of these accounts; doing so could trigger an immediate and expensive tax bill. Instead, you'll update your beneficiary designations to name the trust as a primary or secondary recipient. For life insurance policies, naming the trust as a beneficiary ensures the payout is managed according to your specific instructions rather than being handed over as a lump sum. This coordination is vital when your plan includes Special Needs Planning, as it protects a loved one's eligibility for essential government benefits while still providing for their long-term care.
Massachusetts Real Estate: Navigating the Registry of Deeds
Your home is likely your most significant investment, so ensuring it's properly protected is a top priority. When you're looking at how to fund a living trust in Massachusetts, the most critical step for real estate is the preparation and recording of a new deed. In the Commonwealth, we typically use a Quitclaim Deed to transfer ownership from your individual name to yourself as the trustee of your new trust. This document must be formally recorded at the local Registry of Deeds to be effective. Whether your property sits in the Middlesex South, Middlesex North, or Worcester Registry district, this filing is what officially tells the world that your home is now a trust asset, safely shielded from the probate court.
Recording a deed involves more than just a signature. You'll need to pay a statutory recording fee, which is currently $155 for most deeds in Massachusetts. It's also a vital time to review your Homestead Act protection. Massachusetts law provides an automatic $125,000 in equity protection, but filing a formal Declaration of Homestead can increase that safety net to $500,000. When you transfer your home into a trust, you must ensure your homestead rights are preserved or restated so that your primary residence remains protected from certain creditors. This is a key part of Funding Your Living Trust correctly.
The Trustee’s Certificate (MGL c. 184, § 35)
One of the most common questions we hear is whether you have to put your entire private trust document on the public record. Thankfully, the answer is no. Massachusetts General Law Chapter 184, Section 35 allows for a "Trustee's Certificate." This concise document provides title examiners and the Registry of Deeds with the essential facts they need, such as the name of the trust, who the trustees are, and what powers they hold. A Trustee's Certificate acts as the legal ID card for your trust's authority. By recording this instead of the full trust, you keep your specific distribution wishes and beneficiary names private while still meeting all state recording requirements.
Handling Mortgages and Title Insurance
If you have a mortgage on your home, you might worry that transferring it will trigger a "due-on-sale" clause. However, a federal law known as the Garn-St. Germain Act generally prevents lenders from calling your loan just because you moved your primary residence into a revocable living trust. It's still a wise practice to notify your insurance agent and title insurance company about the change. You want to ensure your policies are updated so that coverage continues seamlessly under the trust's name. This coordination is especially important for complex transfers, such as those involving a Medicaid Asset Protection Trust, where specific look-back periods and eligibility rules apply. Taking these small administrative steps now prevents major headaches for your family later.
Common Funding Mistakes and the 'Pour-Over Will' Safety Net
The most frequent mistake people make is believing the process is finished once the ink is dry and the notary has stamped the documents. It's a natural feeling of relief to have the papers signed, but a trust is only effective if it's active. If you stop there, you've essentially built a high-tech security system but left the front door wide open. You must follow through on how to fund a living trust in Massachusetts by actually moving your titles and accounts. If you buy a new car or finally get that vacation home in the Berkshires, you need to remember to title those in the name of the trust immediately. Life keeps moving, and your estate plan needs to move with it.
This is where the "Pour-Over Will" comes into play. Think of it as a legal safety net. Its job is to catch any assets you might have accidentally left in your individual name. While it's a vital part of a complete plan, it's not the primary goal. If you have questions about your specific assets, you can contact our team for guidance on your funding journey to ensure nothing is left to chance.
Why a Pour-Over Will Isn't a Substitute for Funding
In Massachusetts law, a Pour-Over Will acts as a "catch-all" for your estate. If you pass away with an asset still in your personal name, this Will tells the court to "pour" that asset into your trust. The catch is that this transfer happens through the probate process. This means your family still faces the very costs, public filings, and 12 to 18 month delays you were trying to avoid. The Will and Trust are designed to work together as a unified system; the Trust is your primary vehicle, and the Will is the emergency brake you hope you never have to pull. Relying on the Will as a primary strategy defeats the purpose of the trust entirely.
The Annual 'Trust Audit' Checklist
To stay ahead of these common slips, we recommend an annual "Trust Audit." Every January, take a quiet moment to review your list of assets and see if anything has changed. Did you open a new brokerage account? Did you inherit property from a relative? Major life events like marriage, the birth of a child, or buying new real estate should trigger an immediate update to your funding log. Having a partner who offers an Estate Planning Attorney Flat Fee model makes this ongoing support much easier to manage. You can reach out for help with a deed transfer or a new account without worrying about a surprise bill for every five minute phone call. This proactive stewardship is the best way to ensure your legacy remains secure and your family stays protected.
Securing Your Legacy with Northeast Legal Team’s Flat-Fee Support
Many law firms consider their job done the moment you sign your documents. At Northeast Legal Team, we know that a signature is only the beginning of your protection. We specialize in creating trusts that actually work, which means we don't leave you to struggle with the paperwork alone. David E. Walker and our team act as compassionate mentors, guiding you through the essential final steps of retitling your life's work. We bridge the gap between signing the papers and securing your assets, ensuring your family stays out of the public eye of the probate court.
Mastering how to fund a living trust in Massachusetts shouldn't feel like a second job. Whether your property is in Middlesex or Worcester County, we provide the proactive stewardship you need to move from a state of worry to one of tranquility. We understand the local requirements of the Registry of Deeds and the specific forms required by regional banks. By handling the heavy lifting of deed transfers and providing clear instructions for your financial accounts, we make sure your "empty vault" is filled with the treasures you've worked so hard to build.
Predictable Costs, Permanent Protection
One of the biggest barriers to finishing an estate plan is the fear of hidden costs. Traditional law firms often charge by the hour, which makes clients hesitant to call when they have a question about a new bank account or a deed transfer. Our flat-fee model removes that barrier entirely. When you work with us, your legal fees are capped and transparent from the start. This includes guidance on the funding process, so you can pick up the phone without worrying about a surprise bill. If you're currently helping a loved one manage an estate that didn't have these protections in place, we also offer a Flat Fee Probate Attorney Massachusetts service to provide predictable support during a difficult time.
Your Next Step Toward Peace of Mind
You've already taken the most important step by deciding to protect your family's future. Now, let's make sure that protection is ironclad. We invite you to schedule a consultation to assess your current funding status and identify any gaps in your plan. We take pride in handling the technical details, such as preparing and recording your Trustee’s Certificate and Quitclaim Deeds, so you can focus on what matters most; your family. A fully funded trust is a gift of clarity and ease for your heirs. Let us help you finish the journey and secure the peace of mind you deserve.
Your Path to a Secure and Private Legacy
Signing your estate planning documents is a significant milestone, but your family's protection isn't complete until your assets are properly retitled. A trust only functions as intended when it's active and filled. By taking the time to move your real estate and financial accounts into your trust, you're creating a seamless transition for your loved ones. This proactive step ensures that your private matters stay private and that your hand-picked trustees can act immediately when they're needed most, avoiding the public delays of the probate court.
Mastering how to fund a living trust in Massachusetts is much easier with a compassionate mentor by your side. With over 14 years of experience serving Middlesex and Worcester counties, David E. Walker and our team provide the "plain English" guidance you need to cross the finish line. Our transparent, flat-fee pricing for all trust and estate packages means you can focus on your legacy rather than the clock. You've worked a lifetime to build what you have; it's time to ensure it's fully protected.
Schedule your free estate planning assessment with Northeast Legal Team today. we're here to help you move from a state of worry to a future of tranquility.
Frequently Asked Questions
Do I need to change my Social Security number to a Tax ID for my living trust in Massachusetts?
You don't need a separate Tax ID number for a revocable living trust during your lifetime. Your Social Security number remains the primary identifier for tax purposes, so your annual filing process stays exactly the same. This keeps your administrative work simple while still providing the full legal protection of the trust structure.
What happens if I buy a new house after I've already set up my trust?
You should title any new property directly in the name of your trust at the time of purchase. If you accidentally buy the home in your individual name, you'll need to record a new deed at the local Registry of Deeds to move it into the trust later. Keeping your trust updated as you acquire new assets is a vital part of maintaining your estate's security.
Will funding my trust increase my property taxes in Middlesex County?
Transferring your primary residence into a revocable living trust won't increase your property taxes or trigger a reassessment. Massachusetts law doesn't view this transfer as a "sale" that would change your tax basis. Your local tax bill remains the same, and you'll typically keep any residential exemptions you already have in place.
Can I fund my trust myself, or do I need an attorney for every asset?
You can certainly handle simpler tasks like updating bank account beneficiaries yourself, but having a professional guide is often a relief for more complex assets. While you can request forms from your financial institution, real estate transfers require precise legal drafting. Our team helps you understand how to fund a living trust in Massachusetts by handling the heavy lifting of deed work while you manage the simpler account updates.
How do I move my car or other vehicles into my Massachusetts trust?
To move a vehicle into your trust, you'll need to update the title through the Massachusetts Registry of Motor Vehicles (RMV). Many people choose to keep their everyday vehicles in their individual names to keep their insurance simple. However, for high value collector cars or recreational vehicles, retitling them in the trust's name ensures they avoid the probate process entirely.
Is there a deadline for funding my living trust after I sign it?
There is no strict legal deadline, but your trust only protects the assets it actually holds. If you pass away before an asset is moved, that item will likely have to go through the probate court you were trying to avoid. Starting the funding process immediately after signing your documents is the best way to ensure your family's peace of mind isn't left to chance.
What is a Trustee's Certificate and do I really need one for my house?
A Trustee's Certificate is a concise document that proves your authority to act on behalf of the trust. You absolutely need one for real estate transactions because it provides the Registry of Deeds with essential facts without making your private distribution wishes public. It acts as a legal bridge that satisfies title examiners while keeping your family's private business off the public record.
Does a Pour-Over Will prevent my family from having to go to probate court?
A Pour-Over Will doesn't bypass probate; it actually requires a court process to function. Its job is to catch any assets you forgot to retitle and "pour" them into your trust after you pass away. Learning how to fund a living trust in Massachusetts correctly is the only way to ensure your assets move directly to your heirs without the costs and delays of the probate court system.


