
Imagine your oldest child sitting at the kitchen table, staring at a stack of legal papers while their siblings wait for an inheritance check that hasn't arrived yet. Choosing a family member to manage your legacy feels like a gesture of trust, but it often places a heavy burden on their shoulders during a time of grief. When you weigh the choice of a corporate trustee vs individual trustee, you're really deciding how to protect your family's relationships just as much as your assets. It's a decision that keeps many Massachusetts parents up at night, wondering if they're choosing between a cold institution and a stressed relative.
We understand that you want your estate plan to be a gift, not a source of conflict or confusion. Whether you're concerned about the new 2026 Massachusetts decanting laws or the $2,000,000 estate tax threshold, finding the right path requires a blend of professional expertise and genuine empathy. This guide will help you compare the security of professional management against the personal touch of a loved one. You'll discover how to create a system of accountability that ensures your trust runs smoothly, protects your wealth from mismanagement, and keeps your family peace intact for generations.
Key Takeaways
- Understand the legal weight of a trustee’s fiduciary duty in Massachusetts and how this role helps safeguard your family’s assets.
- Weigh the intimate family knowledge of a loved one against the professional stability of a bank when comparing a corporate trustee vs individual trustee.
- Identify specific "drama factors" within your family to determine if a neutral third party is needed to prevent future inheritance disputes.
- Learn how to assess your asset complexity to ensure your trustee has the right skills to manage everything from simple accounts to Massachusetts real estate.
- Discover how a flat-fee planning process removes financial stress while you design a custom system of accountability for your legacy.
Selecting Your Trustee: Why This Decision Shapes Your Family’s Future
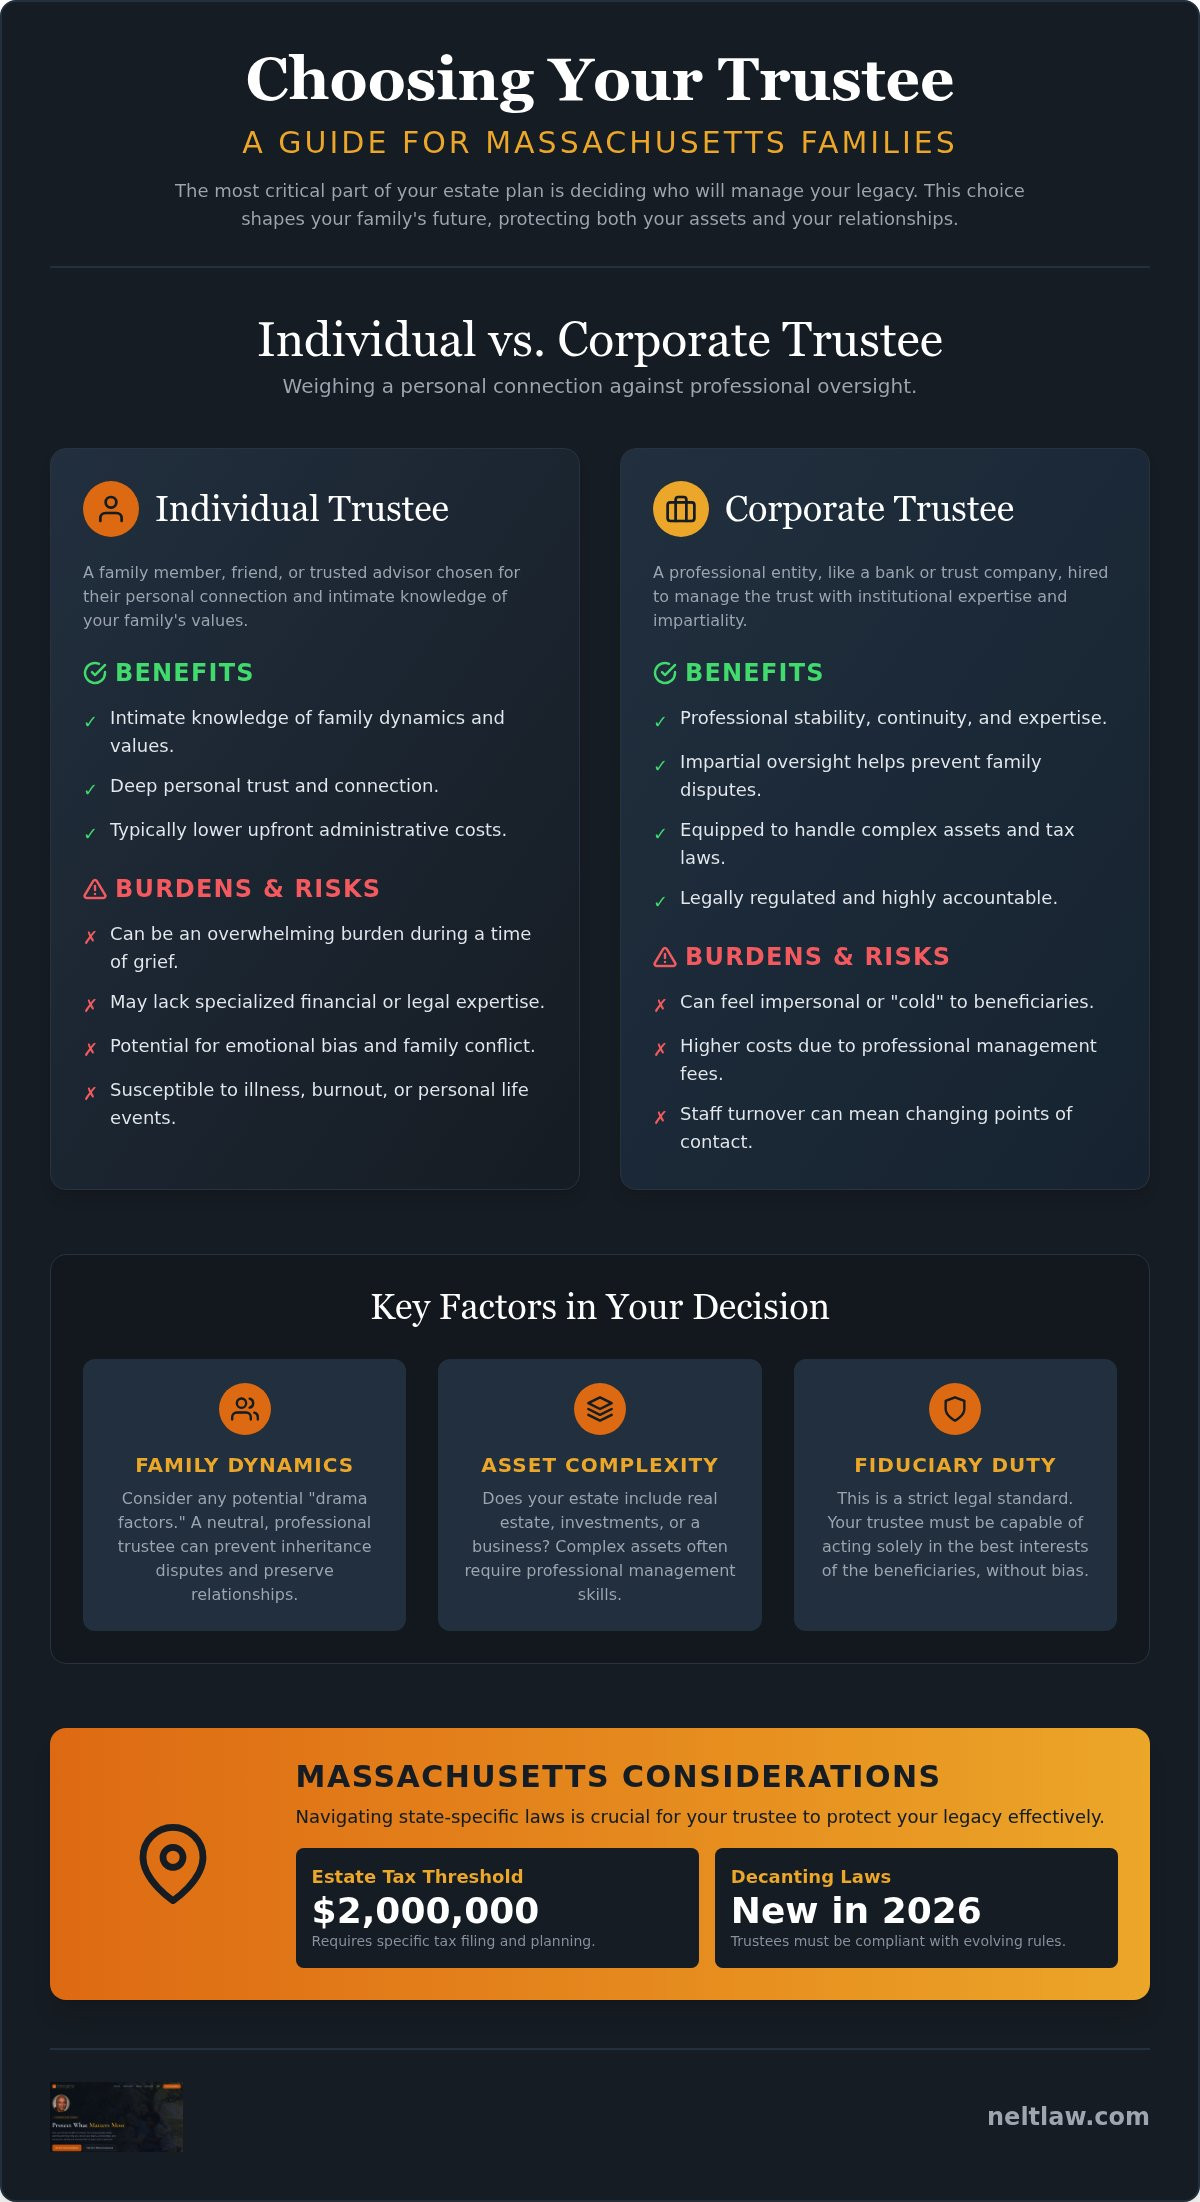
Creating a trust is one of the most proactive steps you can take to protect your family, but the document itself is only as strong as the person or entity you put in charge. A trustee is the person or entity responsible for managing trust assets for your beneficiaries. They step into your shoes when you're no longer able to manage things yourself, ensuring that your wishes are carried out exactly as you intended. This choice is often the most critical part of your estate plan, especially for families in Middlesex County where high-value real estate and complex legacies require a steady, capable hand.
You generally have two paths to consider when finalizing your plan. You can name an individual, such as a spouse, an adult child, or a close friend, or you can hire a corporate entity, like a bank or a professional trust company. Deciding between a corporate trustee vs individual trustee isn't just about who you trust more; it's about who has the time, skill, and emotional distance to handle the work. This decision will determine whether your trust provides a smooth transition for your loved ones or becomes a source of administrative stress and family friction.
The Fiduciary Duty: A Promise of Protection
In Massachusetts, every trustee is bound by a strict legal standard called fiduciary duty. This isn't just a professional suggestion; it's a legal requirement to act solely in the best interest of your beneficiaries, setting aside any personal gain or bias. If a trustee fails this duty, they can be held personally liable for losses or mismanagement under the Massachusetts Uniform Trust Code. This standard acts as a safeguard, ensuring that your assets aren't used as a personal piggy bank or managed carelessly. A fiduciary duty is the legal shield that ensures your legacy is managed with the highest level of integrity and care.
The Burden of Responsibility
Many people name a family member as trustee because they want to "honor" them with the role. However, it's important to recognize that managing a trust is a significant job, not just a title. The person in charge must handle complex tax filings, oversee investment portfolios, and provide detailed accounting to every beneficiary. They must also stay compliant with evolving state laws, including the 2026 Massachusetts decanting rules and specific estate tax filing requirements. If your trustee is an individual who already has a full-time career and a family, this extra workload can quickly become overwhelming.
When an individual trustee feels burdened, mistakes happen. They might miss a filing deadline or fail to communicate clearly with siblings, which often leads to the very family drama you're trying to avoid. At Northeast Legal Team, we act as compassionate mentors to help you weigh these heavy responsibilities. We offer a clear assessment to help you decide if a loved one has the temperament for these tasks, or if the impartial oversight of a professional is a better fit for your family's long-term peace of mind. Our goal is to ensure your plan is a gift to your children, not a full-time job that causes resentment.
The Individual Trustee: Personal Connection vs. Professional Burden
Most people naturally look toward their inner circle when deciding who should manage their legacy. Individual trustees are typically family members, close friends, or long-time trusted advisors who have walked beside you through life's milestones. Choosing a person who knows your heart can feel like the most natural way to ensure your wishes are honored. When you evaluate the choice of a corporate trustee vs individual trustee, the primary advantage of a person is their intimate knowledge of your family's unique dynamics and core values.
While an individual brings a personal touch, it's vital to remember that they are human. They are susceptible to the same life challenges we all face, including illness, burnout, or their own family obligations. Naming an individual can often be a lower-cost option upfront because you aren't paying institutional management fees. However, this choice carries hidden risks if the person you've chosen lacks the specialized financial or legal knowledge required to manage a modern estate in Massachusetts.
The Benefits of Personal Insight
An individual trustee understands the "why" behind your trust. They know if a grandchild in Worcester County has a specific dream of attending medical school or if a family home needs to stay in the bloodline for another generation. This shared history allows for a level of flexibility that a large bank might lack. If a beneficiary faces a sudden emergency, a family member can often react with more speed and compassion than a corporate committee. This personal connection helps maintain your legacy through shared stories and a deep understanding of what you would have wanted in any given situation.
The Risks of Naming a Loved One
The very closeness that makes an individual trustee appealing can also be their greatest liability. Naming one child to manage the inheritance of their siblings can inadvertently spark resentment or "sibling vs. sibling" conflict. This "drama factor" is one of the most common ways that a well-meaning estate plan falls apart. If the trustee feels pressured to say "no" to a brother or sister, it can cause a rift that lasts for decades, turning your gift into a source of family pain.
There's also the danger of inadvertent mismanagement. Even the most well-meaning relative might struggle with the complexities of Massachusetts tax filings or investment oversight. If your trustee moves to another state or becomes incapacitated themselves, your trust could be left in a legal limbo. This is why many families find it helpful to explore protective planning options that provide a safety net for their loved ones. If an individual makes a significant financial mistake, they don't have the institutional insurance that a professional entity provides, leaving your beneficiaries to bear the loss. Choosing the right path means finding a way to keep the personal connection without placing an impossible professional burden on a person you love.
The Corporate Trustee: Professional Continuity and Impartial Oversight
Corporate trustees are professional entities like banks or specialized trust companies. They bring a level of permanence that a person simply cannot provide. When you compare a corporate trustee vs individual trustee, the most striking difference is "institutional memory." Unlike a family member, a corporation doesn't get sick, retire, or find itself caught in the middle of a family feud. It exists as a constant, reliable presence that ensures your trust remains managed exactly as you intended, regardless of how many years pass.
These entities specialize in complex tax laws, sophisticated investment management, and robust asset protection. They're built to handle the heavy lifting that might overwhelm a loved one. One of the greatest benefits is their role as an impartial "bad guy." If a beneficiary makes an unreasonable request for a distribution that goes against your wishes, the corporate trustee can say "no" based on the trust's rules. This shields your family members from being the target of resentment, preserving relationships that might otherwise be strained by money.
Stability and Professional Expertise
For families with high-value or complex trust assets, professional management isn't just a luxury; it's a necessity. Corporate trustees provide continuous oversight, meaning the trust stays managed through every life event. They also maintain strict compliance with rigorous Massachusetts and federal reporting standards. This level of technical accuracy is vital for protecting your wealth from state and federal tax authorities. They have the resources to stay updated on the latest shifts in the law, such as the 2026 Massachusetts decanting rules, ensuring your trust never falls out of compliance.
Common Concerns: Fees and 'Impersonality'
It's common to worry that a bank might feel "cold" or detached compared to a sibling. While they lack personal history, this distance is often what keeps a trust from falling into chaos. Regarding costs, corporate trustees typically charge a percentage of assets under management, which in Massachusetts often ranges from 1% to 2% per year. While this is an ongoing expense, a corporate trustee often saves money in the long run by avoiding costly legal mistakes or tax penalties that an inexperienced individual might trigger. They provide a sense of certainty that your legacy is in expert hands, transforming a technical process into a source of lasting peace for your family.
Comparing the Costs and Risks: A Framework for Massachusetts Families
Deciding on the right management for your trust requires looking beyond the legal documents to the reality of your daily life. You first need to evaluate the complexity of your assets. If your estate consists primarily of simple cash accounts, an individual trustee might manage just fine. however, if you own multi-family real estate in Middlesex County or complex business interests in Worcester, the administrative burden increases significantly. Managing property taxes, maintenance, and rental income requires a level of professional oversight that often exceeds a family member's spare time.
Next, you must honestly assess your family's "drama factor." It's a difficult question to face, but will your chosen individual be able to say "no" when a sibling asks for an early distribution? If the answer is "no," or if saying "no" would destroy their relationship, then an individual trustee might not be the most compassionate choice. By choosing between a corporate trustee vs individual trustee, you're effectively deciding who should carry the weight of those tough decisions.
The Co-Trustee Solution
For many families, the most secure path isn't choosing one over the other, but rather utilizing a "Hybrid Model." By naming an individual and a corporate entity as co-trustees, you create a balance of heart and head. The family member ensures that your values and specific wishes are respected, while the professional handles the technical investment management and tax compliance. This model often provides the best of both worlds, allowing your loved one to focus on family needs without being buried under paperwork.
Splitting these duties can also help manage your planning budget. Understanding how these roles fit into your overall plan is easier when you have a clear picture of the financial commitment involved. You can learn more about how we structure these plans in our guide to Estate Planning Attorney Flat Fee: A Guide to Transparent Legal Costs in 2026. This transparency ensures that the professional oversight you gain doesn't come with unexpected financial surprises.
Questions to Ask Before You Decide
The choice of a corporate trustee vs individual trustee is deeply personal. Before you finalize your decision, sit down with your spouse or a trusted advisor and go through this checklist:
- Does our chosen individual have the time, health, and financial literacy to manage this for the next 20 years?
- Is our family dynamic stable enough for one child to manage the inheritance of another without causing resentment?
- Does the corporate trustee we're considering have a local presence or experience with Massachusetts-specific trust laws?
- If our individual trustee becomes incapacitated, is there a clear and reliable successor ready to step in immediately?
- Will the cost of a professional trustee be offset by the peace of mind and tax-saving expertise they provide?
If you find yourself feeling stuck between these two options, you don't have to decide alone. We invite you to request a personalized estate assessment where we can look at your family's unique situation and help you design a system that protects both your wealth and your relationships.
Finding the Right Balance: How Northeast Legal Team Guides Your Choice
At Northeast Legal Team, we believe our role is that of a compassionate mentor rather than just a legal technician. Designing an estate plan is about more than filling out forms; it's about crafting a family solution that keeps your loved ones safe and united. When you're struggling with the choice of a corporate trustee vs individual trustee, we provide the space and expertise to help you vet your options thoroughly. We don't just ask who you trust. We help you look at the practical reality of who has the capacity to serve your family well for decades to come.
We often facilitate those difficult family conversations that parents naturally want to avoid. If you're worried about how your children will react to a specific trustee choice, we can help you explain the decision in a way that emphasizes protection and love rather than control. Our goal is to ensure that your legacy is a source of peace, not a catalyst for sibling rivalry or administrative chaos. By acting as your protective advocate, we help you build a system of accountability that preserves both your wealth and your family's harmony.
Transparent Planning with Flat Fees
One of the biggest barriers to effective planning is the fear of the billable hour. If you feel rushed by a ticking clock, you might not take the time to explore the nuances of a corporate trustee vs individual trustee. This is why we utilize a flat-fee model for our Living Trusts and other planning services. We believe that flat-fee probate attorney Massachusetts services and estate planning should be predictable and transparent.
Our fixed rates allow for deep, unhurried discussions about your choice of a manager for your assets. You can ask every question on your mind without worrying about a surprise invoice. This transparency creates a safe environment where you can focus entirely on what matters: the long-term security of your family. There is a profound sense of relief that comes from knowing exactly what your legal investment is before we even begin the work.
Your Next Steps Toward Peace of Mind
If you're ready to move from a state of worry to a state of resolution, your next step is simple. We invite you to schedule a consultation where we can listen to your story and help you weigh the risks and benefits of your specific situation. This is a low-pressure opportunity to see how professional guidance can transform an overwhelming process into a manageable path forward. You can also prepare for our meeting by reviewing the Best Estate Attorney Near Me: A Comprehensive Checklist for 2026.
You don't have to carry the weight of this decision alone. We're here to be your friendly guide, ensuring that every choice you make today builds a more secure tomorrow for the people you love most. Let's work together to design a plan that feels like a sigh of relief for you and a lasting gift for your beneficiaries.
Securing Your Family’s Peace of Mind
Choosing the right person or entity to manage your trust is a profound act of love for your family. Whether you find that a personal connection or institutional stability is the best fit, your decision should prioritize long-term harmony and the protection of your legacy. When you evaluate the choice of a corporate trustee vs individual trustee, remember that you don't have to choose between compassion and professional expertise. A well-designed plan can incorporate both, ensuring your assets are managed with technical precision while your family’s unique story remains at the heart of every decision.
At Northeast Legal Team, we bring 14+ years of local Massachusetts experience to help you navigate these sensitive choices with clarity. We provide plain-English guidance and flat-fee pricing for all estate plans, so you can focus on your family’s future instead of worrying about billable hours. We're here to act as your steady hand and supportive ally throughout this journey. Schedule your free consultation with Northeast Legal Team to choose the right trustee for your family. You've worked hard to build your legacy; let's work together to make sure it's protected for generations to come.
Frequently Asked Questions
Can I change my trustee from an individual to a corporate entity later?
Yes, you can typically change your trustee as long as your trust document includes a removal and replacement clause. This flexibility is vital because family situations and financial needs often shift over the years. If your document doesn't have this specific language, the 2026 Massachusetts Uniform Trust Decanting Act may provide a legal path to update your trust's management structure without a long court process.
What happens if my individual trustee dies before I do?
If your primary trustee passes away, the successor trustee you named in your documents will step into the role immediately. It's essential to name at least one or two backups to prevent a gap in management. If no successors are available, a Massachusetts court might have to appoint one, which can add unnecessary stress and delays for your beneficiaries during an already difficult time of grief.
Are corporate trustees only for extremely wealthy families?
Corporate trustees aren't exclusively for the ultra-wealthy, but they do often have minimum asset requirements. Many banks or trust companies look for estates valued at $500,000 or more to make their services cost-effective for the family. When you compare a corporate trustee vs individual trustee, the decision often depends more on the complexity of your family dynamics and assets than just the total dollar amount.
Can a beneficiary also serve as the trustee of their own trust?
Yes, it's very common for a beneficiary to serve as their own trustee, especially in a revocable living trust. However, this can create challenges if the trust is meant to provide asset protection or if the beneficiary struggles with financial management. In these cases, adding a professional co-trustee can provide a layer of oversight that keeps the assets safe from creditors or personal mistakes.
Does a corporate trustee make all the investment decisions?
A corporate trustee usually takes responsibility for investment decisions to meet their fiduciary duty, but you can customize this in your trust. You might choose to give an individual co-trustee the power to oversee specific assets, like a family business or local real estate. This balanced approach ensures that professional growth strategies are used while still respecting the family's unique knowledge of certain legacy holdings.
How much does it typically cost to have a corporate trustee manage a trust?
Most corporate trustees charge an annual fee based on a percentage of the assets they manage, typically ranging from 1% to 2% in Massachusetts. While this is an ongoing expense, it includes professional investment management, tax reporting, and accounting services. When weighing a corporate trustee vs individual trustee, remember that the professional's fee often replaces the separate costs of hiring an outside investment advisor and a dedicated accountant.
Is it possible to name two family members as co-trustees instead of a bank?
You can certainly name two family members as co-trustees, which is a popular choice for parents who want their children to work together. This structure encourages shared responsibility and provides a natural system of checks and balances. The main risk is gridlock if the two individuals cannot agree on a decision. We often recommend including a clear tie-breaking mechanism to ensure the trust continues to function during a disagreement.


